UAE Corporate Tax Registration Deadline: Dates and Fines
The UAE corporate tax registration deadline does not ask you for a single dirham.
That is precisely why businesses get it wrong.
It is not a filing date, it is not negotiable, and it was never yours to choose. It is determined by the month your trade licence was issued. Most owners who missed it did not disagree with the rule. They simply did not look up which row of the schedule they were in, because nothing in the rule asked them for money.
The AED 10,000 that follows does.
Plenty of coverage, including earlier writing on what UAE corporate tax is still misunderstood to be, says the deadlines vary by licence issue date and then stops there. That is the least useful possible way to say it.
So here is the schedule.
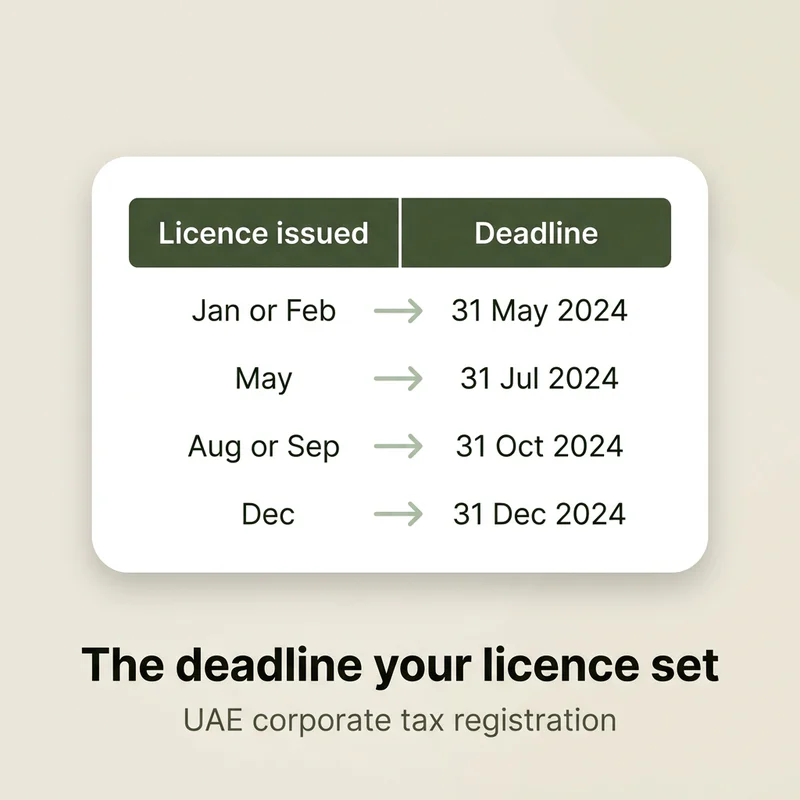
The UAE corporate tax registration deadline, printed in full
The dates come from Federal Tax Authority Decision No. 3 of 2024, which took effect on 1 March 2024.
If your licence was issued before 1 March 2024
| Licence issued in | Registration deadline |
| January or February | 31 May 2024 |
| March or April | 30 June 2024 |
| May | 31 July 2024 |
| June | 31 August 2024 |
| July | 30 September 2024 |
| August or September | 31 October 2024 |
| October or November | 30 November 2024 |
| December | 31 December 2024 |
| No licence held on 1 March 2024 | 31 May 2024 |
The month matters, not the year. A company licensed in June 2009 and a company licensed in June 2023 sit in the same row.
Where a business holds several licences, the earliest one governs. That catches more companies than expected, because the licence an owner thinks of as the main one is often not the oldest one on file.
Every date in that table has passed. A business reading this while still unregistered is not approaching a deadline. It is already late, and the penalty is already there.
If your business started on or after 1 March 2024
Three months from incorporation, establishment or recognition. Free zone entities are included, with no separate track and no grace period.
A company incorporated under foreign law but effectively managed and controlled from inside the UAE gets three months from the end of its financial year instead.
Trading activity is irrelevant. A company that registered a licence, opened nothing, invoiced no one and sat dormant for its first year still owed the registration within three months.
Non-residents and natural persons
A permanent establishment that already existed before 1 March 2024 carried nine months from the date it came into existence. A nexus in place before that date carried a deadline of 31 May 2024.
A permanent establishment arising on or after 1 March 2024 carries six months. A nexus arising on or after that date carries three.
Natural persons come in on turnover. Cross AED 1 million of business turnover in a calendar year and registration is due by 31 March of the following year. Salary does not count. Dividends from listed shares do not count. Rent from a personal home does not count.
None of this involves a judgement call. Your licence date is an administrative fact, and so is your deadline.
The penalty is AED 10,000, and it does not ask whether you owe tax
Cabinet Decision No. 10 of 2024 added late registration to the penalty schedule set out in Cabinet Decision No. 75 of 2023, effective 1 March 2024. The Ministry of Finance put the amount at AED 10,000, matching what late VAT and excise registration already cost.
It is flat. It is charged once, per taxable person, not per licence.
And it is completely indifferent to your profit. A business under the AED 375,000 taxable income threshold pays nothing in corporate tax and still owes the registration. A business claiming Small Business Relief owes it too. Loss-making, dormant, pre-revenue: all of them owe the registration, and all of them owe the AED 10,000 for missing it.
What the rest of the schedule charges
| Violation | Penalty |
| Late registration | AED 10,000, one-off |
| Late tax return | AED 500 per month for the first 12 months, then AED 1,000 per month |
| Unpaid corporate tax | 14% per year, charged monthly on the outstanding amount |
| Failure to keep required records | AED 10,000, rising to AED 20,000 for a repeat within 24 months |
| Late deregistration | AED 1,000, plus AED 1,000 each month, capped at AED 10,000 |
| Not informing the FTA of a change to your tax record | AED 1,000, rising to AED 5,000 for a repeat within 24 months |
Read that table as a sequence rather than a menu.
An unregistered business has no tax record to keep current, no return it can file, and no way to settle a liability it has not declared. One missed registration is what starts the monthly meters running on everything underneath it.

The waiver is open, and it shortens your filing window
In spring 2025 the Cabinet, the Ministry of Finance and the Federal Tax Authority opened a waiver for exactly this penalty, back-dated to cover late registrations from 1 June 2023.
The condition is a filing date. Submit your first tax return, or your annual declaration if you are an exempt person, within seven months of the end of your first tax period rather than the usual nine, and the AED 10,000 is waived. If you already paid it, the amount is refunded to your account with the authority.
There is no form. The relief follows the filing.
Notice what it costs, though. Seven months is two months less than the statutory window, so the waiver does not simply forgive the mistake. It moves your first close forward and makes a faster close the price of the refund. For a business that was late on registration because nobody was tracking dates, that is a demanding trade.
What this actually asks of your books
Registration itself is light work: a trade licence, ownership and authorised signatory detail, a stated financial year, and an EmaraTax account.
The hard part is that corporate tax now assumes your books close on a schedule. A seven-month filing window is not survivable on records that get assembled once a year in a panic, and a chart of accounts built for nothing but a bank reconciliation will not produce a return.
Businesses do not miss the registration deadline because they object to it. They miss it because nobody owned the date.
Put your registration date and your first filing date in the same calendar as your month-end close, owned by the same person.
The AED 10,000 is not a tax on profit. It is a tax on not having a date written down.
---
Try Bizrah free for 14 days — no credit card needed.